A record cash surplus at Indian banks is fading quickly as the central bank keeps liquidity tight to curb bets against the currency.
Excess funds with lenders have shrunk from a high of 11 trillion rupees ($116 billion) in early September to 462 billion rupees as of October 26, according to a Bloomberg Economics index.
The squeeze has intensified since the Reserve Bank of India earlier this month took sweeping measures to defend the rupee as it approached a record low. Analysts at IDFC First Bank and Emkay Global Financial Services expect the crunch to persist, saying the Reserve Bank of India appears reluctant to fully replenish banking system liquidity.
“The tightness seems intentional,” said Madhavi Arora, chief economist at Emkay. The RBI’s actions appear designed to raise the cost of hedging against further rupee weakness and betting against the currency, she said, as higher borrowing costs make it more expensive for traders to borrow rupees and buy dollars.
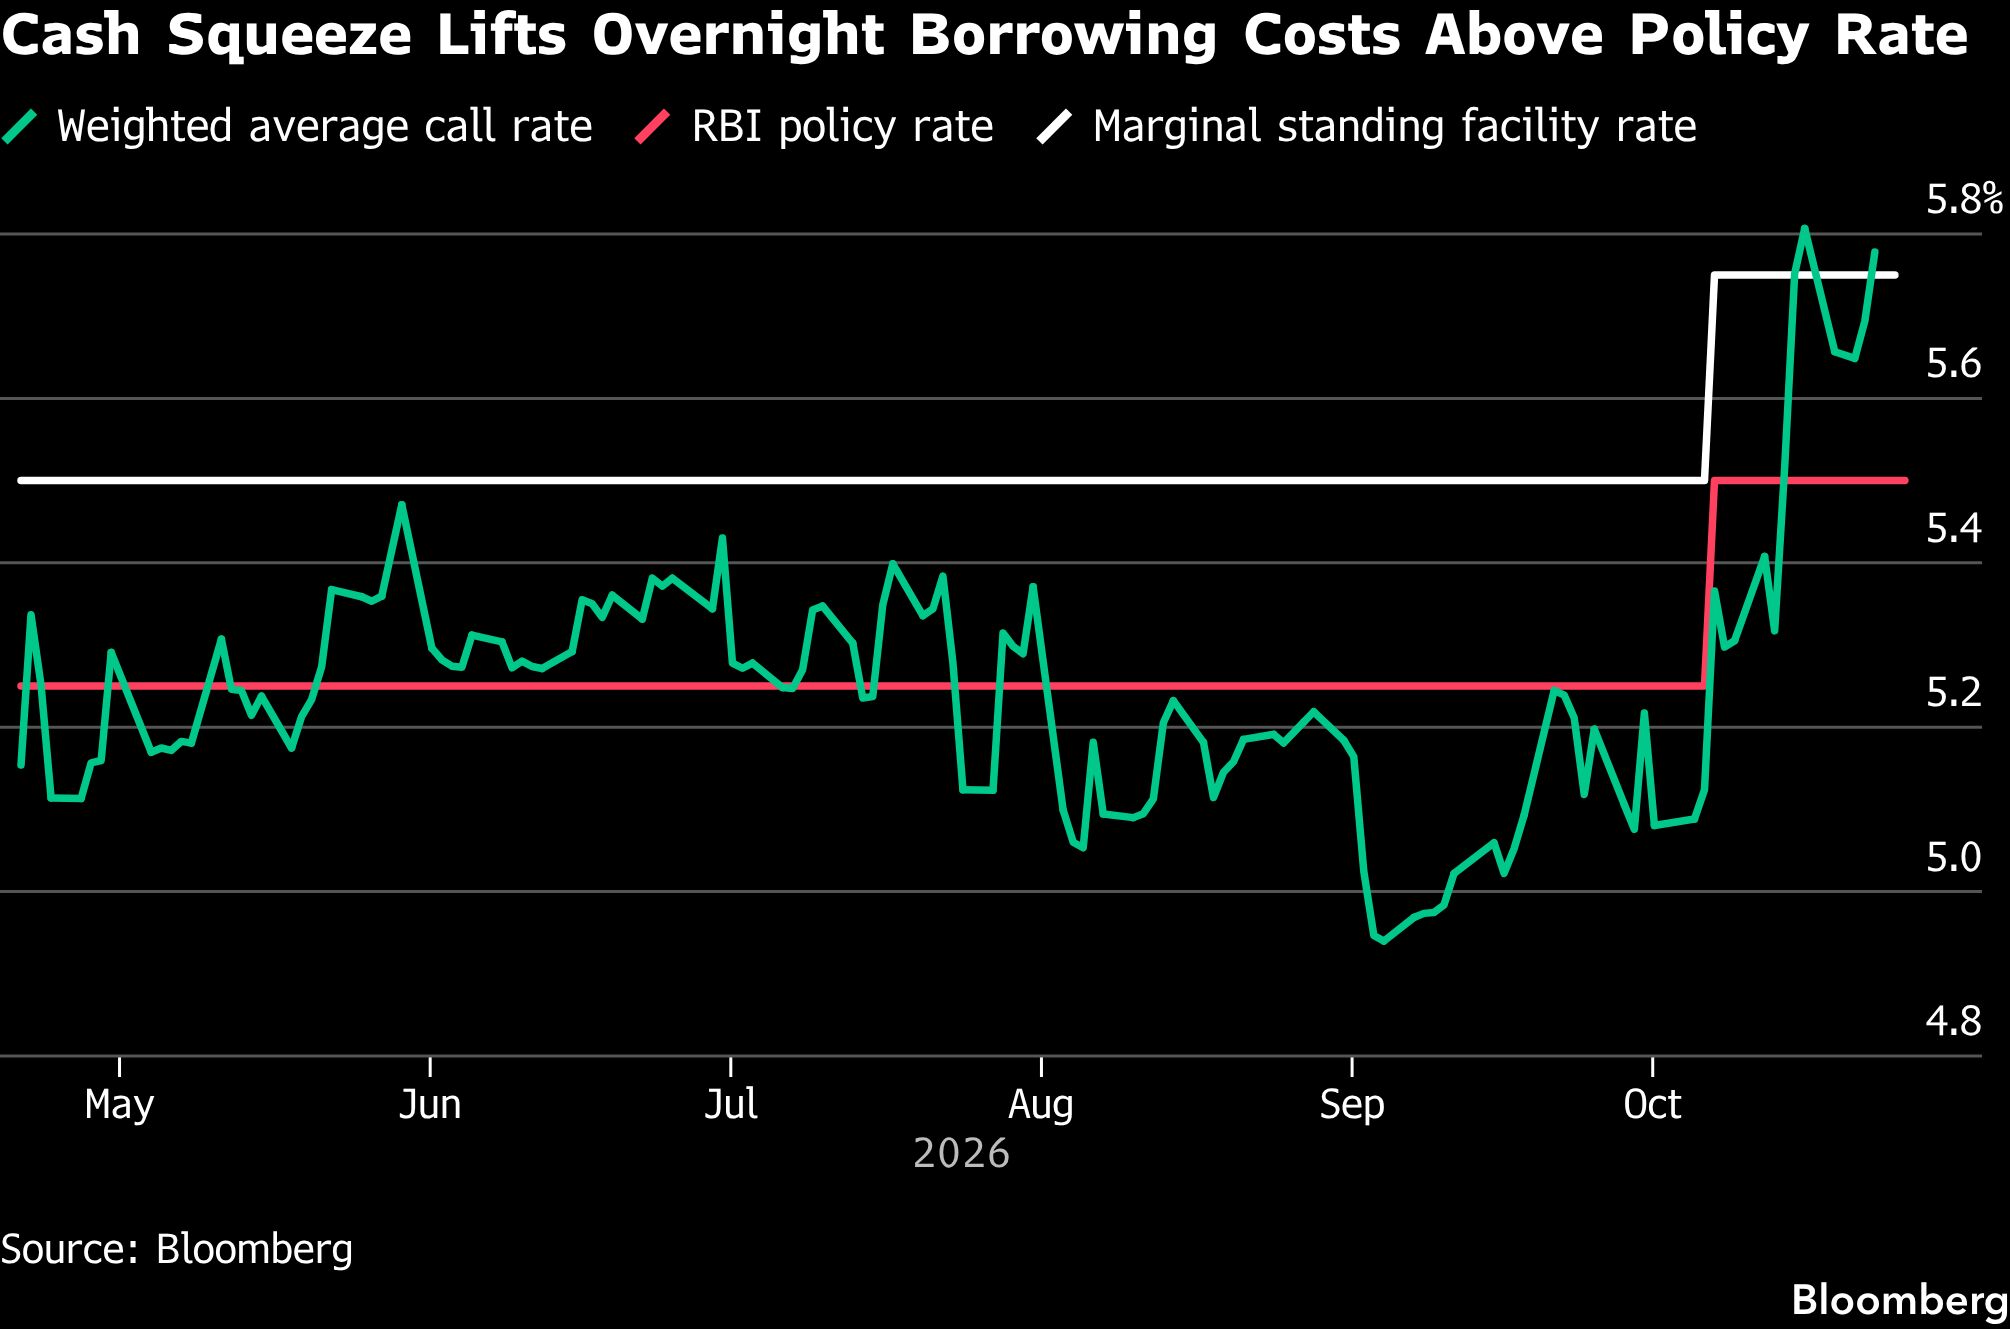
Photo Credit: Bloomberg
The central bank has only offered limited relief. It has so far capped liquidity support at 1.5 trillion rupees, refraining from offering more funds on days when demand has exceeded the amount available.
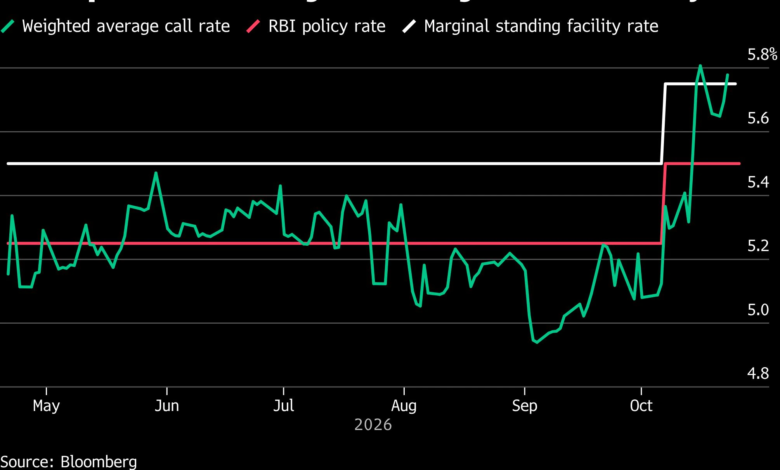
The resulting tightness has pushed overnight borrowing rates close to the top end of the central bank’s policy range.
Governor Sanjay Malhotra said Friday that monetary policy could sometimes be used to address financial-stability risks. Asked whether interest rates could form part of the central bank’s currency-defense toolkit, he said it was something the rate-setting committee “certainly deliberates on.”
The cash crunch is also spreading through domestic funding markets. Rates on fresh three- and six-month certificates of deposit rose about 40-50 basis points last week to a seven-month high. Higher bank funding costs can, in turn, potentially make it more expensive for non-bank lenders to raise money.
“There is a lot of uncertainty on where rates will go from here, but if the macro situation stays as is and crude oil prices inch higher, investors will want a premium on their investments,” said Ajay Manglunia, executive director at Capri Global Capital, a non-bank lender. “The borrowing cost curve can get steeper.”
(Except for the headline, this story has not been edited by NDTV staff and is published from a syndicated feed.)